
Political opinion: Jon Trickett MP - Financial dangers on the horizon
The government’s approach to the finance industry remains dangerously lax, echoing the conditions that led to the 2008 banking crash. The International Monetary Fund (IMF) has issued new warnings, reminding us that those who fail to learn from history are doomed to repeat it.
The lessons of 2008 have not been properly learned. In the run-up to the crash, bankers pursued reckless profits and vast bonuses despite obvious risks. Citigroup’s CEO Chuck Prince captured the mood when he declared, “As long as the music is playing, you’ve got to get up and dance.”
I remember the 2008 banking crash well. First, there were one or two small media stories about curious events in relatively unknown companies in the US banking sector. But it quickly became a torrent and then a cascade of events with the global financial system at serious risk. Hundreds of billions of pounds were spent to prevent total collapse. In the aftermath our public sector was cut to the bone. Essential living costs have skyrocketed, whilst wages and salaries have remained stagnant. Millions of people have been pushed into poverty.
At its heart, the crisis stemmed from two failings: weak regulation and unchecked greed. Senior bankers gambled with other people’s money, confident they’d still receive multimillion pound bonuses. Regulators failed to act. When the crash came no major banker faced criminal prosecution. A few lost their knighthoods, but most escaped unscathed.
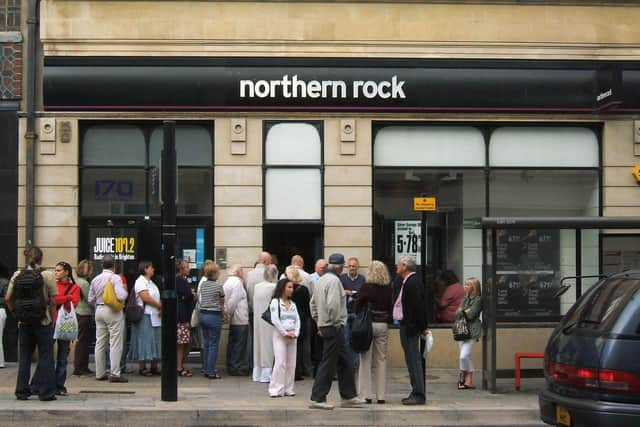

Reforms followed, including a cap on bankers’ bonuses and tighter oversight. Yet the culture of excess persisted. By 2019, the European Banking Authority reported that 3,519 UK bankers earned more than €1 million a year - seven times as many as in Germany. Then Liz Truss’s government scrapped the bonus cap. The Labour government has maintained that decision, while also accelerating the payment of bonuses.
Meanwhile, the Chancellor’s “Leeds reforms” have further deregulated the financial sector. The Bank of England’s Governor, once an ardent advocate of free markets, now cautions against deregulation. His concern is justified: signs of another bubble are emerging. The collapse of two major US private credit companies, First Brands and Tricolor, has raised fears of deeper instability in the global financial system.
One major risk lies in the rise of “shadow banking”. In essence, this is where private credit is funded by investors, insurers, and pension funds rather than customer deposits. These unregulated lenders offer easy credit but create hidden vulnerabilities. The Bank of England recently warned that highly indebted, privately backed firms could default en masse. The IMF now estimates that banks have $4.5 trillion of exposure to the shadow sector. This is greater than the entire UK economy.
Given the immense capacity of the finance sector to damage society, loosening controls and rewarding risk is reckless. A Labour government should defend the public interest, not court another disaster. It’s time to stop the music and demand a new social contract - one that ensures banks serve the people and not the other way around.